CN
 EN
The Federal Reserve raised its benchmark interest rate by 25 basis points to a target range of 3.75% to 4% on September 16, 2026, marking its first-rate hike since 2023. More important than yesterday’s hike is the message that another hike remains on the table. Sixteen of 18 policymakers reportedly see another increase in 2026.
- The dollar index moved toward a five-week high following the Fed decision as markets priced in the possibility of further tightening. The strength of the dollar and the possibility of further tightening keep currency pairs like USD/JPY, USD/INR volatile and worth watching.
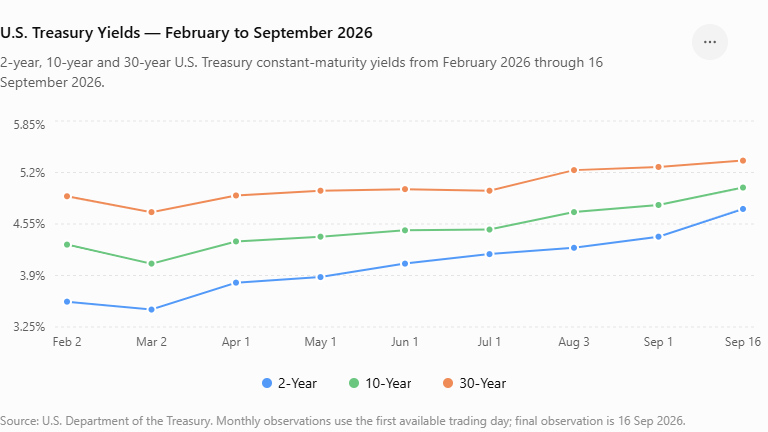
- The 2-year yield rose about 7.5 bp to 4.738%, its highest close since July 2024. This is the most direct signal of markets repricing the path of Fed policy. 10-year yield climbed to 5.00%, around a 19-year high, but the move looks modest because the market is also looking at whether tighter Fed policy eventually slows growth and inflation. 30-year yield: actually fell about 1.7 bp to 5.346%, so the move was not uniformly higher across the curve.
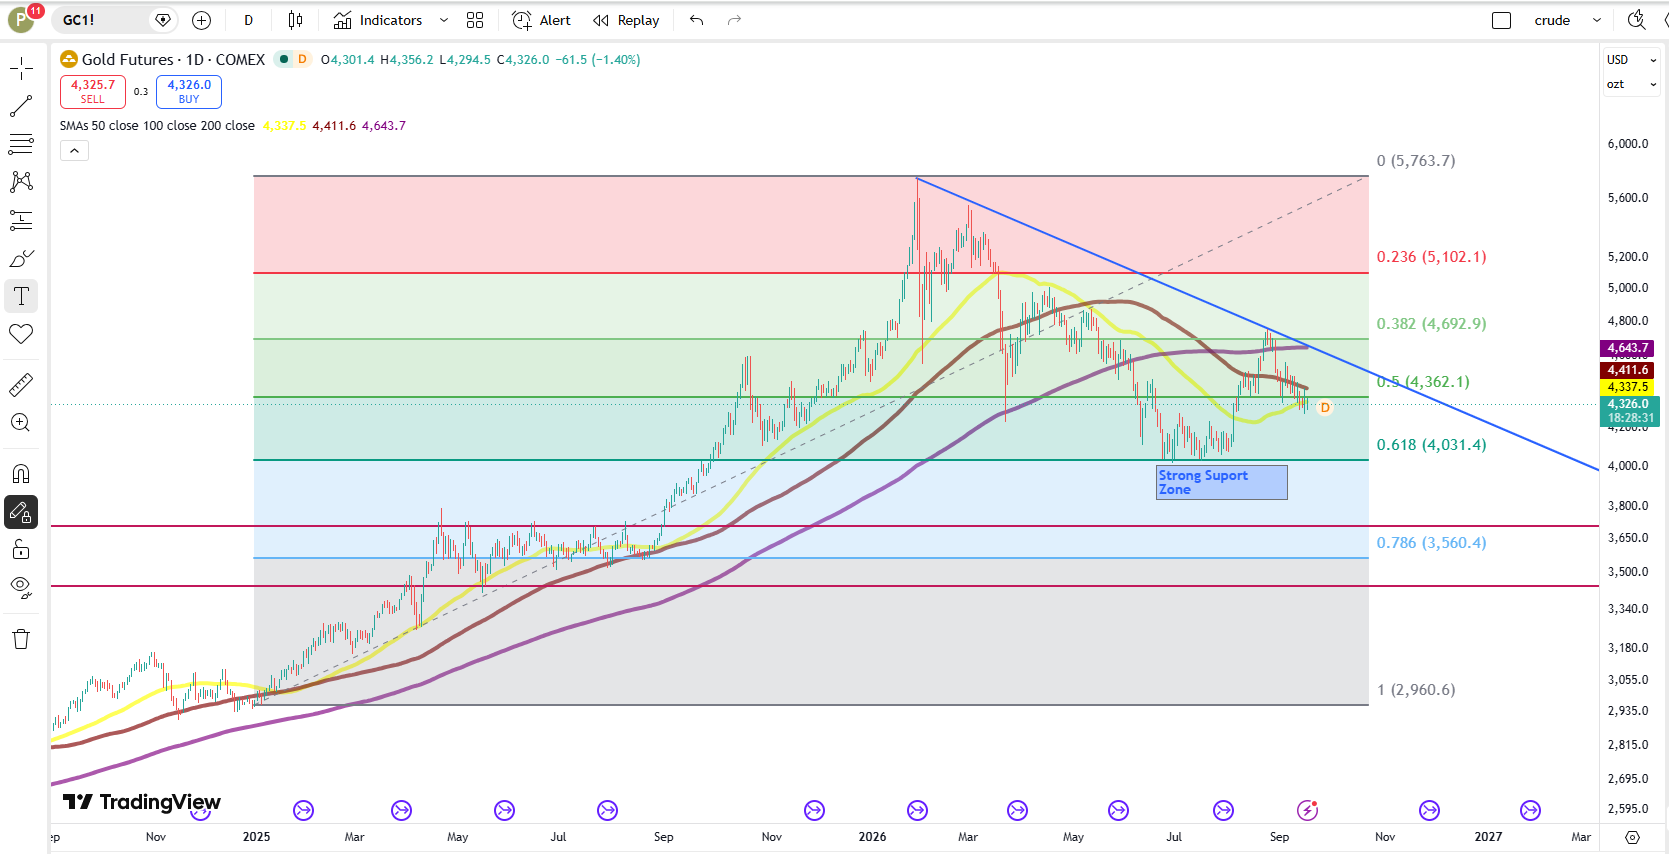
- Gold fell more than 1% after the Fed decision, with spot gold around $4,240/oz after briefly trading above $4,365. A stronger dollar and higher-for-longer rate expectations are weighing on bullion, even as Middle East risks and broader market uncertainty remain supportive.
- Silver fell around 1.1%, with the same higher-yield/stronger-dollar pressure affecting precious metals.
- The Asian reaction has been less negative than Wall Street. The broader Asian picture was mixed rather than outright risk-off. Korea and Taiwan had already shown resilience from AI/memory demand, while bargain-hunting in semiconductor names provided support.
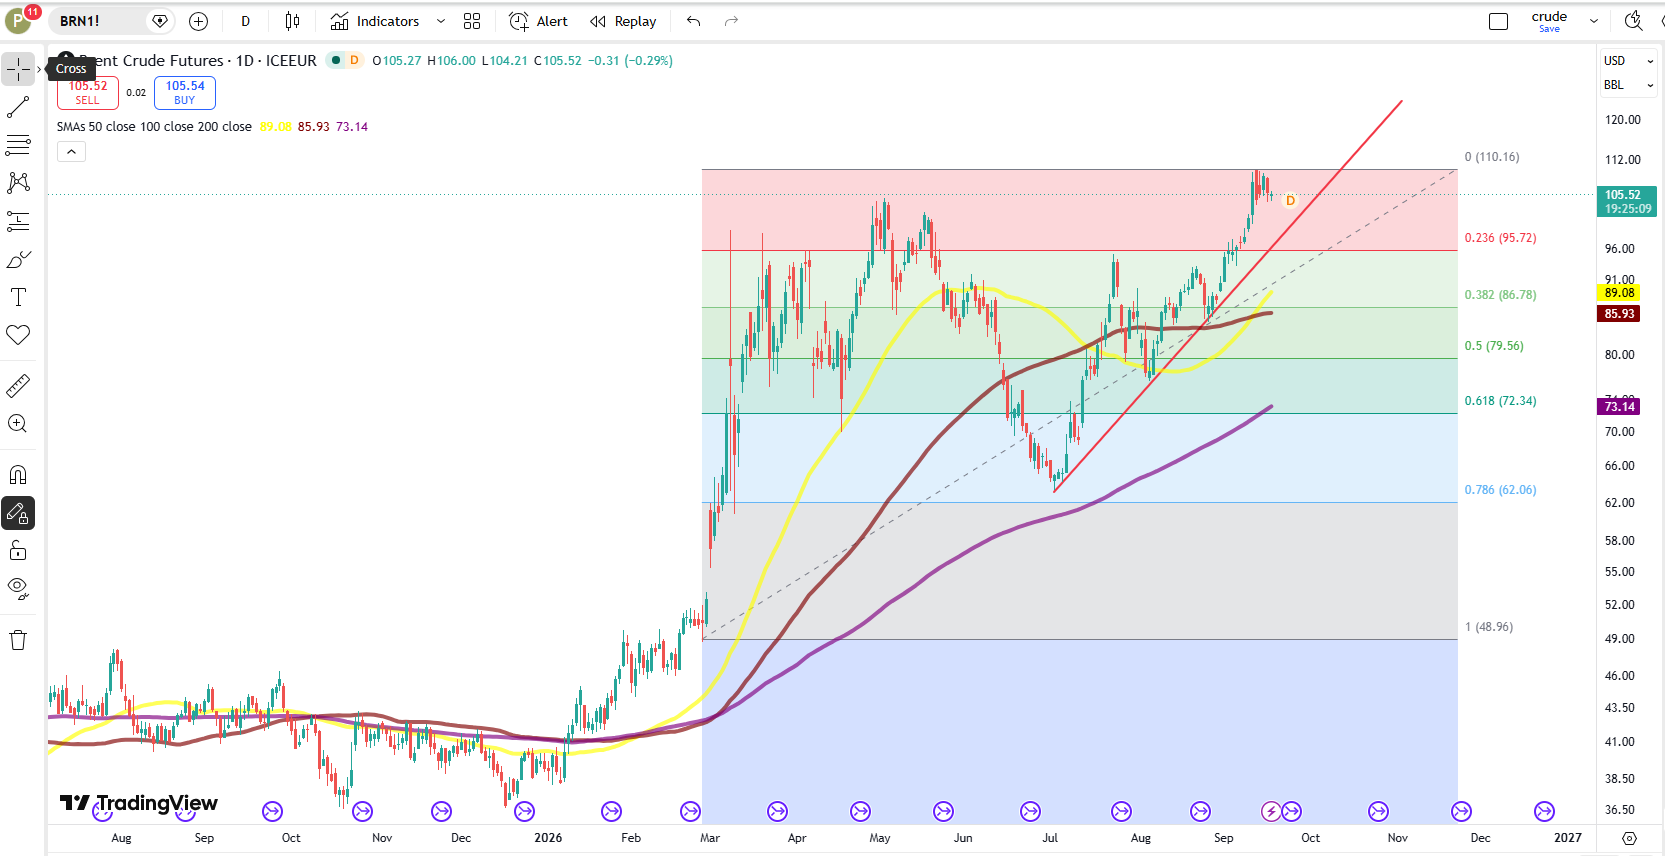
- Oil retreated over 3% overnight, but this wasn’t primarily a Fed-driven oil sell-off. While some of the pullback can be attributed to Dollar strength, the decline was linked more to signs that Saudi Arabia is finding alternative export routes through Oman and that its East-West pipeline could potentially restart soon.
The bigger message: this was not just a 25-basis-point move
For markets, the important takeaway is the change in the expected path of interest rates rather than the 25-basis-point move itself.
The Fed has effectively flipped from rate cuts to rate hikes compared to the beginning of 2026. The latest projections indicate that policymakers are not treating the September hike as necessarily a one-off event. Reuters reported that 16 of 18 policymakers see at least one more increase this year.
This creates a more complicated environment for investors because markets now have to price two opposing forces. On one side, higher oil prices can keep inflation elevated and in turn force the Fed to remain restrictive. And on the flip side, higher-for-longer rates eventually weaken economic growth.
What happens if another hike comes into the picture?
The possibility of another 25-basis-point increase means markets are likely to become increasingly data-sensitive and Volatile.
A stronger-than-expected inflation reading, accompanied by elevated energy prices, could push Treasury yields and the dollar higher again. That would potentially put renewed pressure on gold, silver and high-duration equities.
Conversely, elevated Oil prices and borrowing costs will weaken demand, and softer inflation or employment data could reduce expectations for another hike. In that scenario, the dollar and front-end Treasury yields could ease, while gold and rate-sensitive equities could find support.
Treasury yields: the market’s most important signal
The Treasury market may now be more important than the headline Fed Funds rate.
The sharp rise in the 2-year yield to around 4.74% shows that the market is immediately repricing the expected path of monetary policy. The 10-year yield at around 5% is also significant, but the behaviour of the longer end of the curve needs to be watched carefully.
The fact that the 30-year yield moved lower while the 2-year and 10-year yields rose shows that the market is not simply pricing “higher rates everywhere.” Instead, investors are weighing higher near-term inflation and policy rates against the possibility that tighter monetary conditions eventually slow growth.
For investors, the 2-year yield, 10-year yield and the spread between them could therefore become useful indicators of whether markets are primarily trading an inflation story or a growth story.
Gold and silver: expect two-way volatility
Gold’s reaction illustrates the conflict currently facing precious metals. Higher yields increase the opportunity cost of holding a non-yielding asset, while a stronger dollar makes gold more expensive for non-dollar investors. Both factors can pressure bullion. However, geopolitical uncertainty, elevated oil prices, fiscal concerns, and central-bank demand can continue to provide a floor for gold.
This means investors should be cautious about interpreting one sharp post-Fed decline as the beginning of a sustained downtrend. Meanwhile, if yields and the dollar continue rising together, gold could face additional short-term pressure. If yields stabilise while geopolitical or fiscal concerns remain elevated, dips in gold could attract buyers.
Silver could remain more volatile because it combines precious-metal characteristics with industrial demand exposure. A stronger dollar and higher yields are negative, but expectations for industrial demand can create additional two-way price action.
Equities: valuation meets the cost of money
The immediate reaction in US equities was negative, with markets reversing earlier gains after the Fed decision. Reuters reported declines in major US indices following the announcement.
The key issue for equities is not simply whether rates are higher, but how long they remain higher. Higher discount rates can pressure valuations, particularly for growth and technology companies whose valuations depend heavily on future earnings. At the same time, a resilient economy and strong corporate earnings can partially offset the impact of higher rates.
Investors should therefore watch whether market weakness remains concentrated in high-duration growth stocks or starts spreading into banks, industrials, consumer stocks and the broader market.
Oil remains the inflation wildcard
Oil is now directly connected to the Fed story. For now, we think the $100 oil price is driving inflation and signalling the Fed to raise rates, rather than being a reaction. The key debate in the oil market still revolves around whether physical flows are actually recovering, or is the market is simply pricing in temporary relief in supply logistics.
If Saudi Arabia successfully restores alternative export flows and the East-West pipeline comes back online, part of the geopolitical premium could unwind. However, this does not automatically mean that the physical oil market has returned to normal. Recent price action in Oil already shown how quickly prices can move when the market perceives a change in physical supply risk. For traders, this means oil could continue to see large intraday swings even without a major change in the Fed outlook.
Singapore markets: banks versus REITs
Singapore markets deserve particular attention because the impact of higher US rates is likely to be different across sectors.
Singapore banks
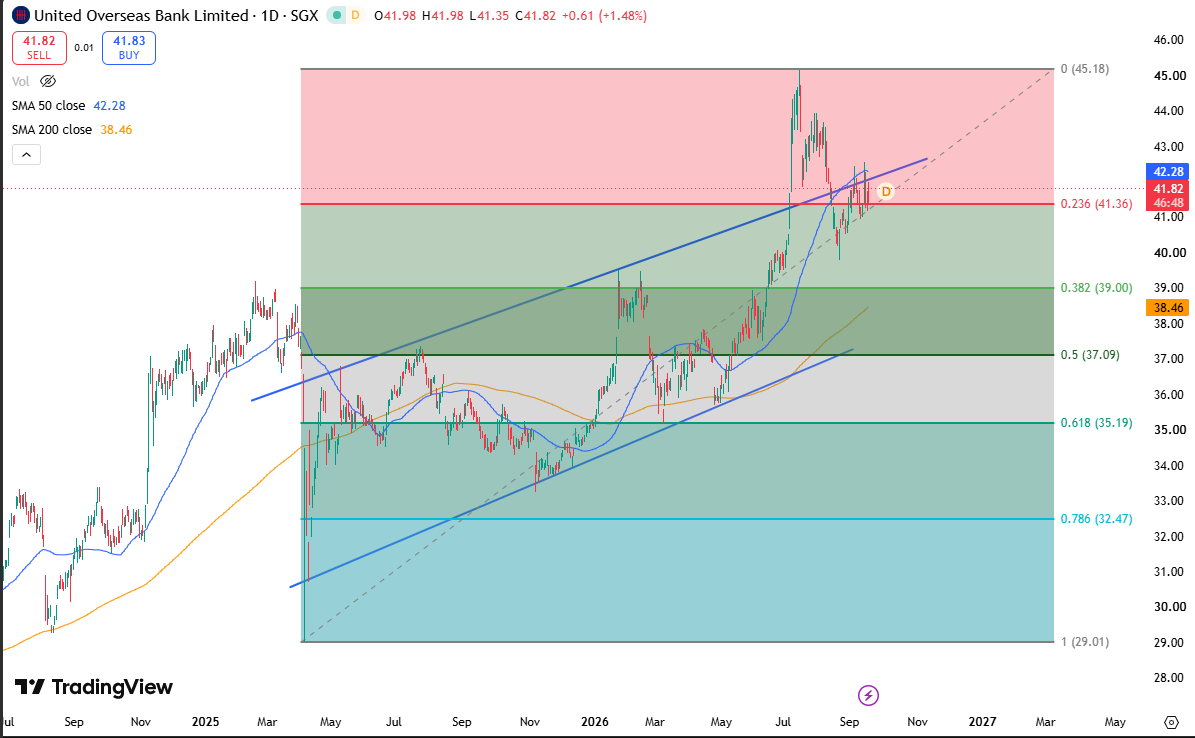
At first, Singapore banks, DBS, OCBC and UOB, can initially be relatively more resilient in a higher-rate environment because lending rates and asset yields can reprice higher.
However, the benefit is not unlimited. If rates remain elevated for longer, banks also face higher funding costs, potentially slower loan demand and a more challenging credit environment. Net interest margins therefore need to be watched alongside loan growth and asset quality rather than looking at interest rates in isolation.
What is imperative to understand is that a single additional rate hike can be supportive for bank margins, but a prolonged tightening cycle can eventually become a growth and credit-quality issue.
Singapore REITs
The transmission mechanism is more direct for REITs. Higher interest rates increase the cost of refinancing debt and can reduce the relative attractiveness of REIT yields compared with government bonds and other fixed-income assets.
However, Singapore REITs have already shown that the immediate market reaction does not have to be uniformly negative. Singapore’s major REITs opened broadly flat to slightly higher after the latest Fed decision, highlighting that investors are also looking at whether the rate move was already priced in.
The risk increases if the market starts pricing in multiple additional hikes rather than just one more 25-basis-point move.
Bottom line
The September Fed hike has changed the market conversation from “when will rates fall?” to “how much further could rates rise?” For investors, the immediate question is therefore not simply whether the Fed hikes again. It is whether oil, inflation and economic data force markets to price that next hike more aggressively
The dollar and front-end Treasury yields are now key signals for the direction of currencies and precious metals. Equities face the challenge of higher discount rates, while Singapore banks and REITs could experience very different effects from the same higher-rate environment. And most importantly, Oil remains the biggest potential wildcard because it is simultaneously an energy-market story and an inflation story.
Interested to dive deeper?
Here are some prompts you can ask our NOVA.I on the NOVA platform:
- Does bargain-hunting in semiconductors post-hike signal real conviction in AI/memory demand, or just that the sector was oversold beforehand?
- If Singapore REITs already priced in this hike, what are some potential catalysts that would cause them to re-rate downward from here?
- How would sustained higher interest rates affect the AI infrastructure build-out across Big Tech?
Take a view now
Trade CME E-nano Index Futures at just $0.50* on NOVA, or monitor prices on related commodities, precious metals, ETFs, CFDs and Stocks now. 立即开立账户.
在 NOVA 交易 CFDs、ETF、外汇、期货、期权、贵金属和股票
NOVA 交易功能
- 接通超过 20 个全球交易所 通过超过 20 个全球交易所的 200 多个环球期货产品,把握市场机会。
- 全球股票交易机会 覆盖新加坡、美国、中国、香港、马来西亚及日本市场超过 11,000 只股票和 ETF。
- TradingView 图表支持 查看实时图表,并使用超过 100 种技术指标。
- 真正的多资产交易 通过 NOVA 的单一账簿,交易 CFDs、ETF、外汇、期货、期权、贵金属及股票。
- 美元及新元股票融资利率低至 4.5% p.a.
- 美股碎股低至 1 美元起
以低至 1 美元名义金额开始投资美股碎股,每笔订单佣金为 0.38 美元。