CN
 EN
After holding rates steady for more than a year, the US Federal Reserve has raised interest rates for the first time since 2023. For Singapore investors, the key question may not be whether the hike is good or bad for markets, but how different parts of the market could respond.
On 16 September 2026, the Federal Open Market Committee voted unanimously to raise the federal funds rate by 25 basis points to a target range of 3.75% to 4.00%. The move marks a reversal from the easing cycle that began in 2024 and signals the possibility that interest rates could remain higher for longer than markets previously expected. The Fed also indicated that inflation remains elevated and that additional tightening could still be considered.
For Singapore investors, the effects are unlikely to be felt evenly.
Banks, REITs and the broader equity market may each respond differently depending on how higher rates influence earnings, financing conditions and investor sentiment.
What Does History Tell Us?
When the Fed raises rates, many investors instinctively expect equities to struggle. However, evidence-based investing encourages a different approach. Rather than assuming how markets should react, it looks at how they have behaved during previous cycles.
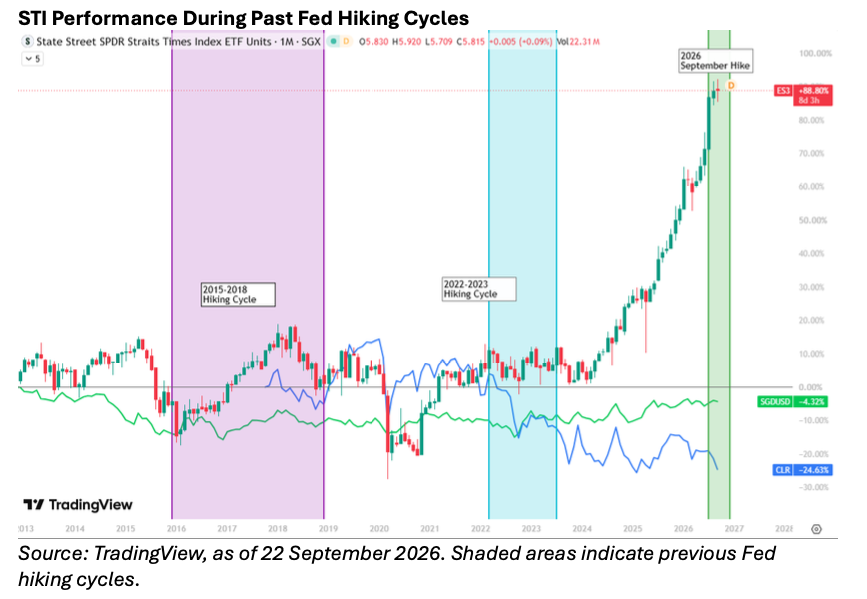
Looking at the historical performance of the STI ETF, one observation stands out: Fed hiking cycles have not automatically translated into prolonged declines in Singapore equities.
During the 2015-2018 hiking cycle, the STI experienced both periods of weakness and recovery. During the 2022-2023 hiking cycle, Singapore equities remained broadly range-bound before subsequently moving higher.
This does not mean the market will necessarily respond the same way today. Every cycle is different.
What it does suggest is that interest rates are only one factor influencing market performance. Corporate earnings, economic growth, capital flows and sector composition often matter just as much.
For long-term investors, broad benchmarks such as the Straits Times Index can therefore serve as a reminder that market outcomes are often driven by more than a single Fed decision.
How Singapore’s Banks Could Respond to Higher Rates
Singapore’s banks spent much of 2026 dealing with margin pressure as interest rates declined.
A higher-rate environment could gradually reverse some of that pressure by supporting lending yields and net interest margins.
However, the benefits are unlikely to be immediate.
Changes in US monetary policy take time to flow through to Singapore’s interest-rate environment, and banks must also wait for loans and deposits to reprice.
As a result, any meaningful improvement in net interest margins may become more visible in 2027 than during the remaining months of 2026.
In the meantime, non-interest income remains an important earnings driver.
Recent results from DBS, OCBC and UOB highlighted the growing contribution from wealth management, trading and other fee-generating businesses. These businesses may continue to play a key role even if the rate environment becomes more supportive.
The key question investors may be watching is which earnings engine proves more important over the next year: a recovery in net interest margins or continued growth from fee-based businesses.
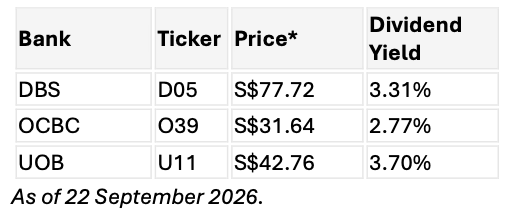
Why Higher Rates Could Remain a Challenge for REITs
If banks could eventually benefit from a higher-rate environment, REITs face a different set of considerations.
Many REITs rely on debt to finance property acquisitions and operations. As borrowings mature, refinancing at higher rates can increase financing costs and potentially affect distributions.
The challenge is not limited to borrowing costs.
REITs are frequently valued against government bond yields and other income- generating assets. When interest rates rise, investors may demand higher yields from REITs, creating additional valuation pressure.
Many Singapore REITs have mitigated some of this risk through fixed-rate borrowings and hedging strategies. However, refinancing cycles eventually bring financing costs closer to prevailing market rates.
This means investors will likely continue monitoring financing costs, debt maturity profiles and refinancing activity across the sector.
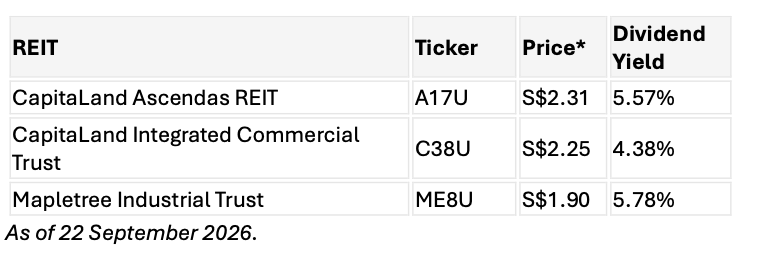
Wondering how this rate hike could ripple through to DBS, OCBC and UOB’s dividends – or squeeze REIT payouts further? Ask NOVA.I, the AI assistant built into the Nova trading app, to walk through the connection.
One Market, Different Time Horizons
The Fed’s latest decision also highlights an important distinction between long-term investing and short-term market views.
For long-term investors, broad benchmarks such as the STI and the MSCI Singapore Index offer diversified exposure to Singapore equities across multiple sectors.
History shows that corporate earnings, dividends, economic growth and capital flows can influence long-term returns just as much as changes in interest rates.
However, not all investors approach the market with the same time horizon. Some may have a shorter-term view on how Singapore equities could react to developments such as Fed decisions, inflation data releases or earnings announcements.
For investors researching short-term tactical opportunities linked to the broader Singapore market, the Phillip-Nova MSCI Singapore Daily (2X) Leveraged Product (SGX: LSS) and Phillip-Nova MSCI Singapore Daily (-1X) Inverse Product (SGX: SSS) are both linked to the MSCI Singapore Index. They are commonly researched by investors with a short-term view that Singapore equities may either strengthen or weaken following major market developments.
The key distinction is therefore not simply market direction, but investment horizon. While broad market indices are often used by investors seeking longer-term exposure to Singapore equities, products such as LSS and SSS are designed around short-term tactical market views.
What Investors Should Watch Next
Several developments could determine how the Fed’s latest decision ultimately affects Singapore markets:
SORA and Bank Margins – The speed and extent to which Singapore’s interest-rate environment responds could influence whether banks see a meaningful improvement in net interest margins.
Bank Earnings – Wealth management, trading and other non-interest income businesses may remain just as important as the direction of rates.
REIT Refinancing Activity – Debt maturity schedules and financing costs will provide clearer evidence of how REITs are being affected by a higher-rate environment.
Broad Market Participation – The STI and MSCI Singapore Index will help show whether market movements are concentrated within individual sectors or supported more broadly across the market.
Future Fed Decisions – Any further changes to inflation expectations or Fed policy could influence how markets reassess the outlook for rates.
Access Singapore Market Opportunities Through Phillip Nova
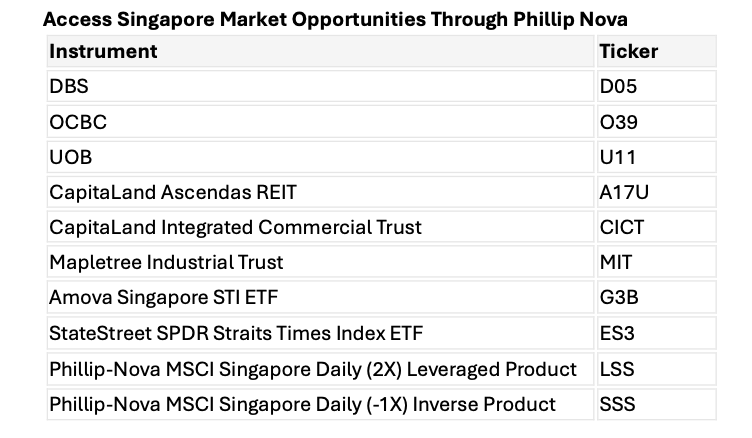
DBS, OCBC, UOB, the featured REITs, LSS and SSS are all available through a Phillip Nova account. LSS and SSS are Specified Investment Products designed around daily investment objectives and are generally researched by investors with short-term tactical views on the Singapore market.
Whether your focus is on long-term exposure to Singapore’s blue chips and index benchmarks, or shorter-term opportunities arising from major market events such as Fed decisions, today’s market offers investors a broader range of tools than ever before.
For investors building a Singapore allocation, access to both individual stocks and market-linked products can make it easier to express different views on the same market while staying aligned with their own objectives and risk tolerance.
投资新加坡市场,享开户礼遇
获取 40 FREE LSS Shares* when you open a new NOVA Trading Account and invest S$1,000 in SGX-listed stocks or ETFs. Find out more here.
在 NOVA 交易 CFDs、ETF、外汇、期货、期权、贵金属和股票
NOVA 交易功能
- 接通超过 20 个全球交易所 通过超过 20 个全球交易所的 200 多个环球期货产品,把握市场机会。
- 全球股票交易机会 覆盖新加坡、美国、中国、香港、马来西亚及日本市场超过 11,000 只股票和 ETF。
- TradingView 图表支持 查看实时图表,并使用超过 100 种技术指标。
- 真正的多资产交易 通过 NOVA 的单一账簿,交易 CFDs、ETF、外汇、期货、期权、贵金属及股票。
- 美元及新元股票融资利率低至 4.5% p.a.
- 美股碎股低至 1 美元起
以低至 1 美元名义金额开始投资美股碎股,每笔订单佣金为 0.38 美元。