CN
 EN
关键要点
- US crude inventories unexpectedly rose by 1.02 million barrels, versus expectations for a draw, adding to signs of improving near-term supply.
- US-Iran tensions remain unresolved, even as Qatar continues efforts to facilitate talks between Washington and Tehran.
- Higher Treasury yields and a stronger US dollar are adding another variable for oil, potentially influencing demand for dollar-denominated crude.
Crude oil remains highly sensitive to developments between the US and Iran, but improving physical supply is beginning to provide some relief.
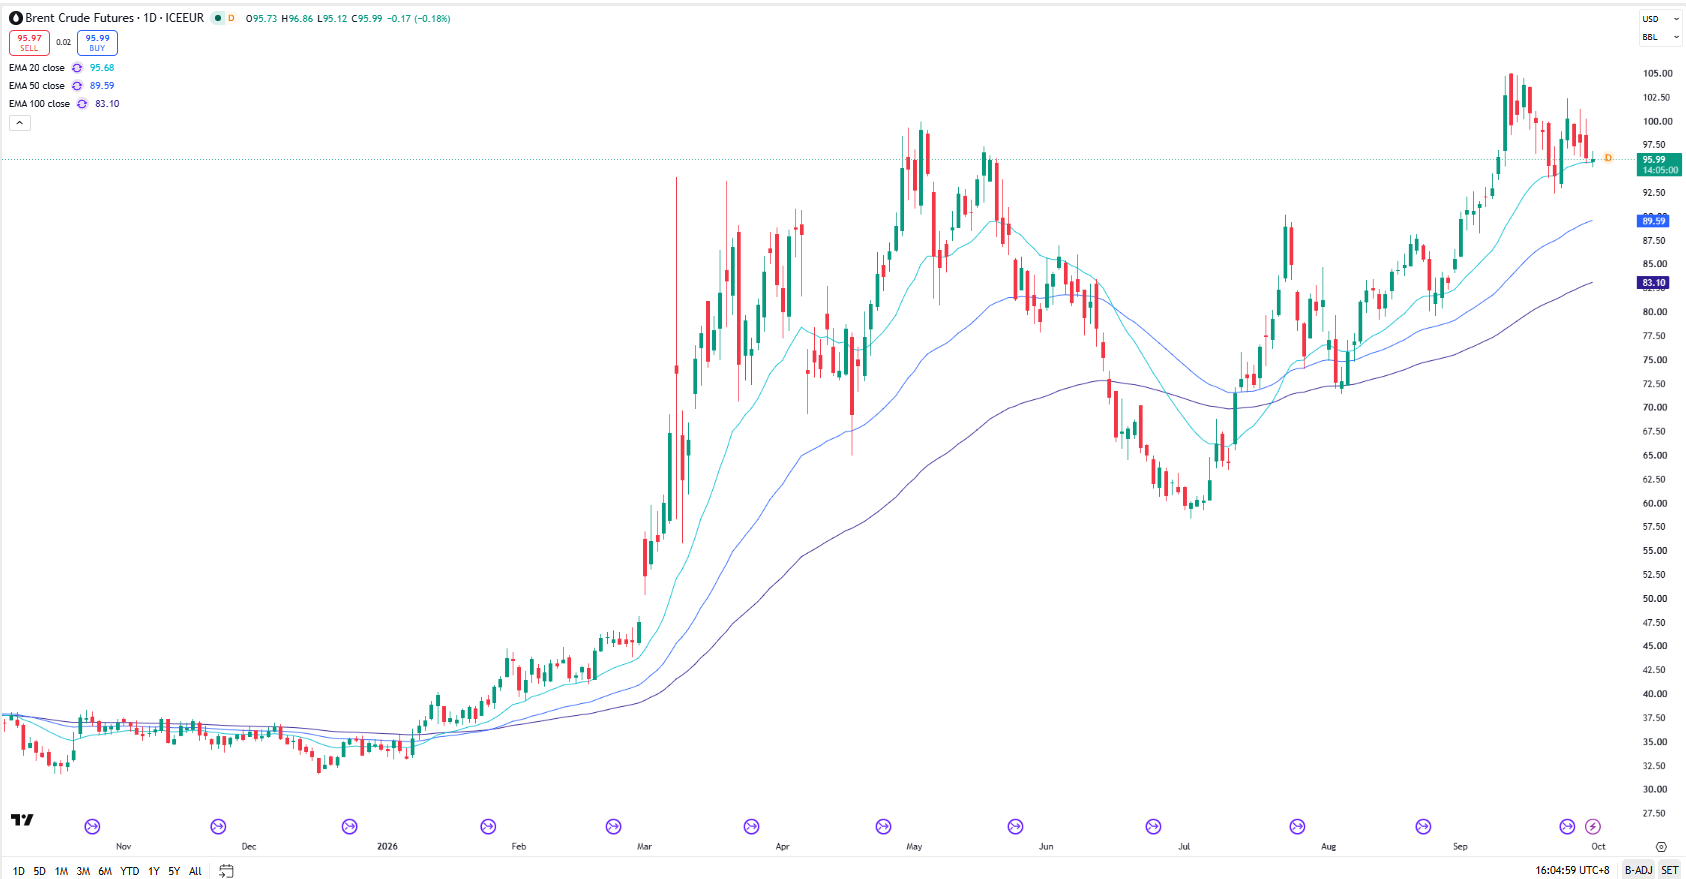
Brent crude traded around US$103.73 a barrel in early Wednesday trading, while WTI was around US$89.72. Brent is on track for a monthly gain of roughly 14%, while the spread between Brent and WTI has widened to a four-month high.
The latest move followed renewed uncertainty over US-Iran relations after US President Donald Trump denied reports that he was prepared to ease sanctions on Iran. At the same time, Qatar continues to mediate between Washington and Tehran, leaving oil caught between the risk of further escalation and the possibility of a diplomatic breakthrough.
Middle East Supply Is Recovering
Beyond the headlines, one of the most important developments for oil is the gradual recovery in Middle Eastern exports.
Regional crude exports rose to around 16.33 million barrels per day (bpd) in September, the highest level since the conflict began in February. However, exports remain approximately 3.2 million bpd below pre-war levels.
Saudi Arabia has also resumed exports through its East-West Pipeline, providing an important alternative route to the Strait of Hormuz.
Alternative routes cannot fully replace the volumes normally transported through Hormuz, but they can help reduce the immediate impact of disruptions to shipping through the strait. This means investors may increasingly need to watch actual physical flows, rather than geopolitical headlines alone.
US Inventories Add Another Supply Signal
Supply pressures are also shifting in the US.
The latest API estimate showed that US crude inventories increased by 1.02 million barrels in the week ended 25 September, compared with expectations for a decline of around 1.9 million barrels. Gasoline inventories also increased, while distillate stocks declined.
Meanwhile, Washington has offered to exchange up to another 40 million barrels from the Strategic Petroleum Reserve (SPR) as part of a coordinated international programme aimed at supporting global oil supply. The US SPR currently holds fewer than 284 million barrels, its lowest level since 1982.
The additional barrels could provide near-term supply relief, although the lower level of the reserve leaves less of a buffer should another major disruption occur.
The Dollar and Rates Enter the Equation
Macro conditions are also becoming increasingly important to oil’s next move.
Longer-term US Treasury yields recently climbed to multi-year highs, with the 10-year yield touching 5.293% and the 30-year reaching 5.621% before easing. Elevated oil prices have contributed to inflation concerns, while resilient economic data and expectations around future Fed policy have also influenced yields.
At the same time, the US dollar has strengthened, gaining around 2% in September. Because crude oil is priced in US dollars, a stronger dollar can make oil more expensive for buyers using other currencies, potentially weighing on demand at the margin.
This creates an important feedback loop to watch:
Higher Oil → Inflation Concerns → Higher Rate Expectations/Yields → Stronger Dollar → Potential Headwind for Oil
The relationship is not automatic, but it highlights why oil traders may increasingly need to watch bond and currency markets alongside developments in the Middle East.
What Should Investors Watch Next?
Oil is currently caught between geopolitical risk and improving physical supply.
US-Iran tensions and uncertainty surrounding the Strait of Hormuz continue to support a geopolitical risk premium. Yet Middle Eastern exports are recovering, alternative routes are being utilised, US crude inventories have risen, and additional SPR barrels could provide further near-term supply relief.
If physical flows continue to improve and US-Iran tensions ease, part of that geopolitical premium could unwind. Conversely, renewed disruption to shipping or energy infrastructure, or a deterioration in diplomatic efforts, could put supply risks back in focus.
For investors, the next move in oil may depend on which force wins out: geopolitical risk, recovering supply, or mounting macro pressure from yields and the US dollar.
Navigate the Crude Oil Futures and Options market on NOVA, or monitor prices on related ETFs, CFDs and stocks now. 立即开立账户.
在 NOVA 交易 CFDs、ETF、外汇、期货、期权、贵金属和股票
NOVA 交易功能
- 接通超过 20 个全球交易所 通过超过 20 个全球交易所的 200 多个环球期货产品,把握市场机会。
- 全球股票交易机会 覆盖新加坡、美国、中国、香港、马来西亚及日本市场超过 11,000 只股票和 ETF。
- TradingView 图表支持 查看实时图表,并使用超过 100 种技术指标。
- 真正的多资产交易 通过 NOVA 的单一账簿,交易 CFDs、ETF、外汇、期货、期权、贵金属及股票。
- 美元及新元股票融资利率低至 4.5% p.a.
- 美股碎股低至 1 美元起
以低至 1 美元名义金额开始投资美股碎股,每笔订单佣金为 0.38 美元。