CN
 EN
By Priyanka Sachdeva, Head, Market Insights, Phillip Nova
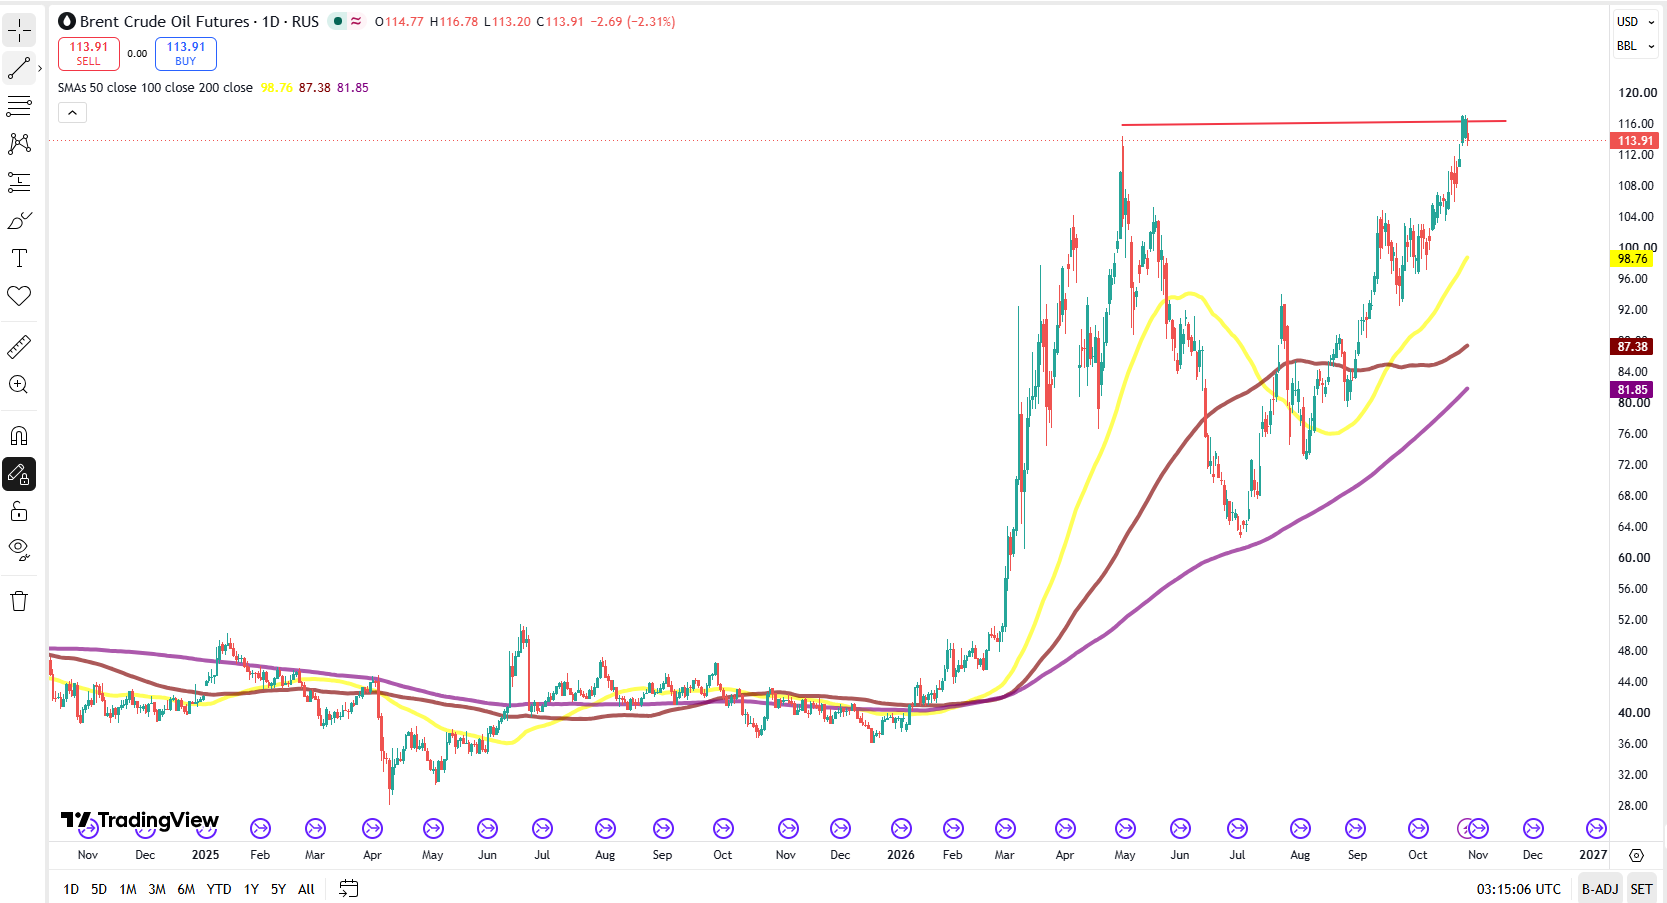
Brent struggles near US$116 while gold defends the US$4,000 level. Are we witnessing an emerging inverse relationship between oil and precious metals?
One interesting trend I have been observing in recent weeks is the increasingly interconnected movement between global macroeconomic developments, oil prices and precious metals, particularly gold and silver. Traditionally, geopolitical uncertainty has been viewed as supportive of both oil and gold. However, the current market environment appears to be challenging that relationship. Higher oil prices are no longer necessarily translating into stronger safe-haven demand for gold. Instead, the inflationary consequences of elevated energy prices, their impact on treasury yields and expectations surrounding Federal Reserve policy seem to be driving these asset classes in opposite directions.
Brent crude rallied sharply last week, settling at US$116.72 per barrel on 23 October, its highest settlement since April. The rally was driven largely by renewed concerns over Middle Eastern energy infrastructure, Houthi attacks involving Saudi Arabia and the continuing uncertainty surrounding the US-Iran conflict. The widening Brent-WTI spread, exceeding US$13 per barrel at Friday’s settlement, also highlights how international supply risks and transportation disruptions are being priced more aggressively into Brent than into the US benchmark.
However, despite these developments, Brent has struggled to sustain its advance beyond the US$116-117 region. The repeated rejection around these levels raises the possibility of an emerging double-top formation, although a confirmed technical reversal would require a more decisive break below intervening support. For now, I see this as an important resistance zone rather than a confirmed bearish reversal.
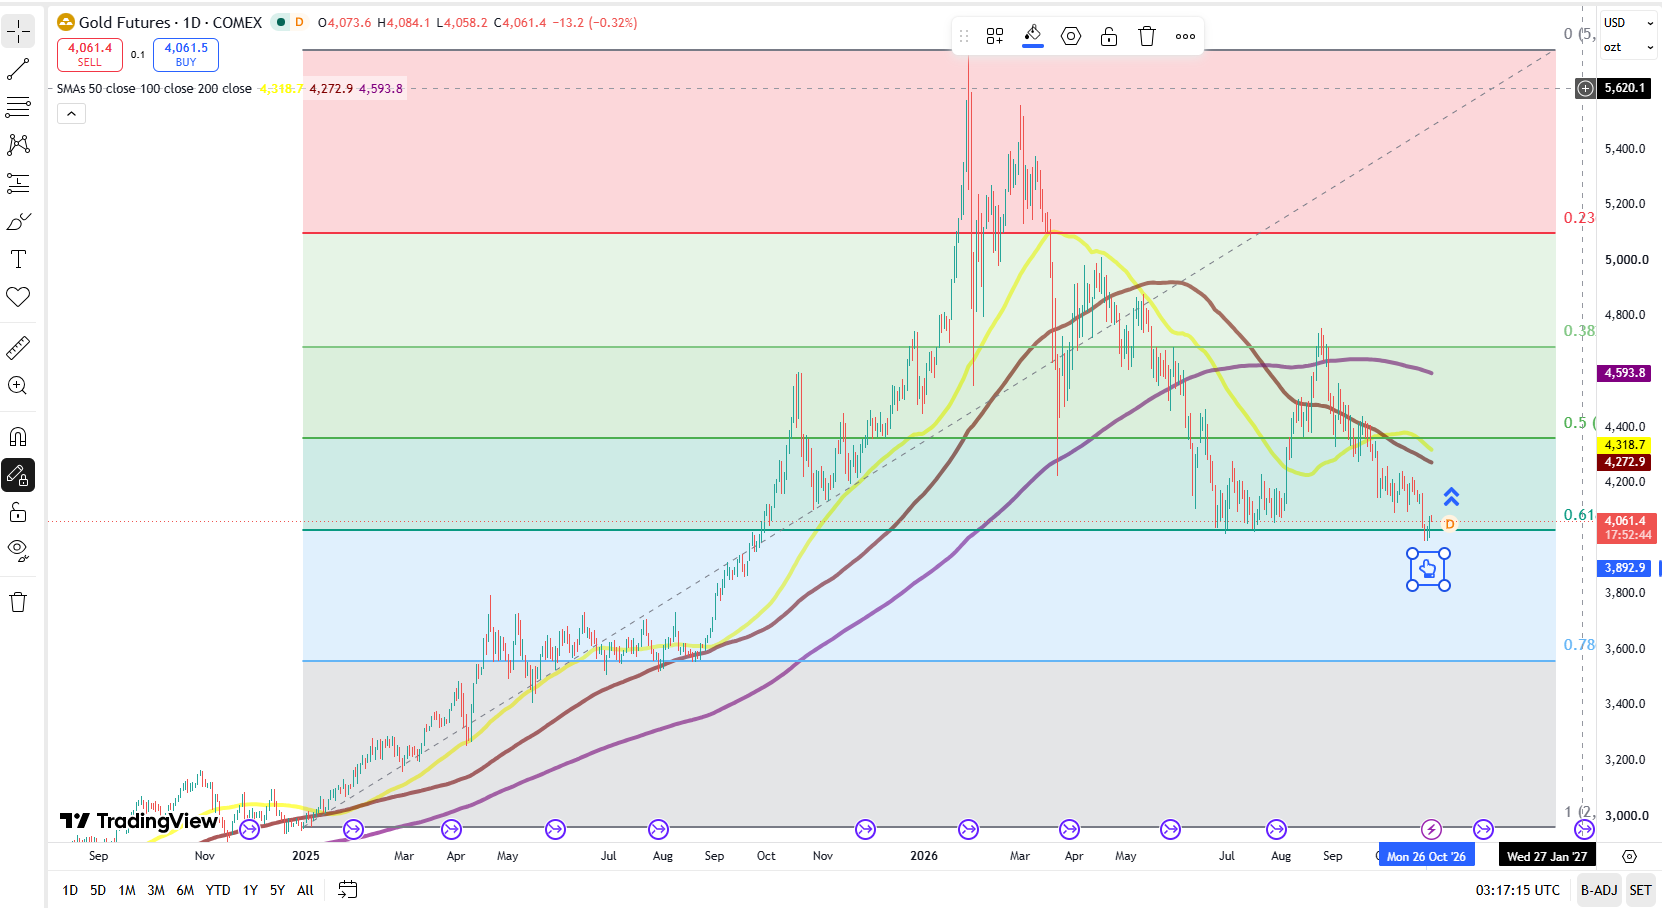
Interestingly, gold has demonstrated almost the opposite behaviour. As Brent rallied last week, gold came under considerable selling pressure, briefly slipping below the psychological US$4,000 level. Yet, as oil prices subsequently retreated on renewed diplomatic hopes, gold recovered. This price action strengthens my view that the relationship between oil and precious metals deserves closer attention, rather than treating their movements as independent trends.
The transmission mechanism is relatively straightforward. Elevated oil prices raise concerns over inflation, particularly when energy costs remain high for a prolonged period. Higher inflation expectations complicate the Federal Reserve’s policy outlook, potentially forcing policymakers to maintain restrictive interest rates for longer or consider further tightening. This, in turn, supports treasury yields and potentially the US dollar, both of which can weigh heavily on non-yielding assets such as gold and silver.
In other words, the very geopolitical risks that would ordinarily support gold through safe-haven demand are simultaneously creating macroeconomic conditions that work against it. When risk-free returns become increasingly attractive, investors have less incentive to hold assets that generate no income, unless their expectations of capital appreciation or financial instability are sufficiently strong.
This relationship becomes particularly relevant ahead of the Federal Reserve’s 28 October policy decision, followed by US inflation data and the 3 November midterm elections. Markets are widely anticipating that the Fed will leave interest rates unchanged at 3.75-4.00% this week, although expectations of another rate increase later in the year remain significant. US 10-year treasury yields have also been hovering around 5%, reinforcing the opportunity-cost argument against precious metals.
Meanwhile, uncertainty surrounding President Trump’s next move on Iran remains a critical variable. With oil prices already elevated and the midterm elections approaching, any diplomatic breakthrough or measure that eases supply concerns could remove some of the geopolitical premium from crude. Conversely, further attacks on oil infrastructure, shipping routes or export facilities could quickly reverse the recent correction.
My base observation is that if Brent retreats further, gold and silver could find room to recover, even without a meaningful improvement in their standalone fundamentals. Lower oil prices could ease inflationary pressure, temper expectations of further monetary tightening and potentially provide relief to treasury yields and the dollar. Such a combination would be more supportive of precious metals, particularly after their recent corrections.
Conversely, a sustained breakout in Brent above US$120, could reignite inflation concerns and put gold’s US$4,000 support under renewed pressure. There is, however, an important distinction. This inverse relationship should not be treated as permanent. A sufficiently severe geopolitical escalation, financial-market dislocation or loss of confidence in conventional assets could still generate simultaneous demand for oil and gold.
For now, Brent’s rally appears to be encountering resistance near US$116-117, while gold continues to attract buying interest around the psychological US$4,000 level. Whether these levels hold will depend on developments in the Middle East, the Federal Reserve’s policy communication and the direction of US treasury yields. My key observation is that the next meaningful move in gold may not originate in the gold market itself. It could well be triggered by what happens in oil.
Navigate the Gold and Crude Oil Futures and Options market on NOVA, or monitor prices on related ETFs, CFDs and Stocks now. 立即开立账户.
点击 此处 to learn more about our 1-Ounce Gold and 100-Ounce Silver Futures promotion now.
点击 此处 to learn more about our Micro Crude Oil Futures and Options promotion now.
在 NOVA 交易 CFDs、ETF、外汇、期货、期权、贵金属和股票
NOVA 交易功能
- 接通超过 20 个全球交易所 通过超过 20 个全球交易所的 200 多个环球期货产品,把握市场机会。
- 全球股票交易机会 覆盖新加坡、美国、中国、香港、马来西亚及日本市场超过 11,000 只股票和 ETF。
- TradingView 图表支持 查看实时图表,并使用超过 100 种技术指标。
- 真正的多资产交易 通过 NOVA 的单一账簿,交易 CFDs、ETF、外汇、期货、期权、贵金属及股票。
- 美元及新元股票融资利率低至 4.5% p.a.
- 美股碎股低至 1 美元起
以低至 1 美元名义金额开始投资美股碎股,每笔订单佣金为 0.38 美元。