EN
 CN
The first edition of Japan: 2+2 looks at two distinct parts of Japan’s market. Mitsubishi Corporation and an ETF focused on trading houses and resources illustrate the capital allocation and resource story. Advantest and a semiconductor ETF offer two ways to examine Japan’s role in advanced chip production.
In this edition:
- Mitsubishi
- Advantest
- Global X Japan Wholesale Trade & Resource Business ETF
- Global X Japan Semiconductor ETF
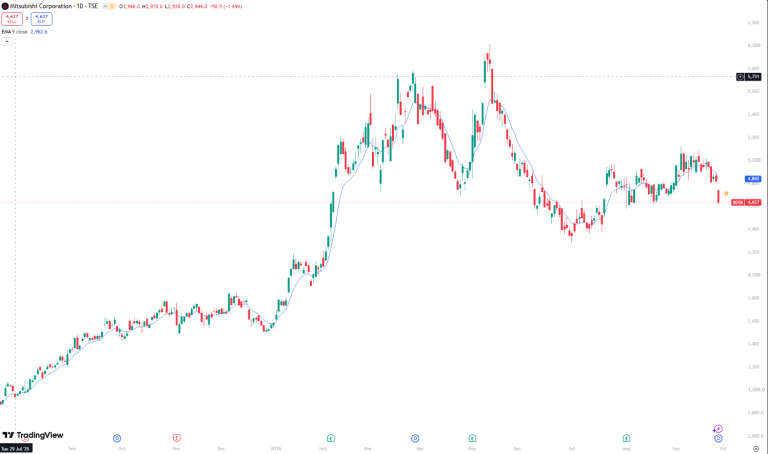
Mitsubishi Corporation (TSE: 8058)
WHY IT IS IN FOCUS
A diversified Japanese trading house spanning resources, industrial activities and global commerce.
WHAT TO MONITOR
- Q2 revision: management flagged a likely upgrade to the ¥1.10trn forecast
- Segment mix — is non-resource profit growing faster than resources?
- Underlying operating cash flow against the ¥1.25trn target
- Capital recycling: divestment proceeds and where they are redeployed
- Progress to the 12%+ ROE target; net debt-to-equity as JGB yields rise
BULL CONSIDERATIONS
- FY3/27 guidance ¥1.10trn net income vs ¥800bn actual FY3/26
- Q1 FY26 net income ¥298.5bn, +47% YoY — 27% of guidance
- DPS raised to ¥125 (from ¥110); progressive dividend policy
- Management targets ROE of 12%+ by FY2027 under Strategy 2027
BEAR CONSIDERATIONS
- FY3/26 net income fell 15.8%; profit before tax −21.3%
- Q1 beat was FX- and coal/copper-price led, not structural
- Conglomerate mix: Global Environmental Energy, Materials and Mobility all declined
- Re-rating to ~¥18trn market cap leaves less valuation cushion
KEY DATA
SHARE PRICE / MARKET CAP ¥4,947 · ¥18.1trn Close 22 Sep 2026; roughly US$115bn. | FY3/27 GUIDANCE ¥1,100bn NI EPS ¥300.42; underlying operating cash flow ¥1.25trn. | Q1 FY26 (APR-JUN) ¥298.5bn, +47% Revenue ¥5,181bn +22.8%; FCF positive at ¥185.3bn. |
SHAREHOLDER RETURNS DPS ¥125 (+13.6%) Progressive dividend; treasury holdings up sharply on buybacks. | LAST REPORTED YEAR ¥800.5bn, −15.8% FY3/26 revenue ¥18.9trn +1.6%; PBT −21.3% on prior-year one-offs. | NEXT CATALYST Q2 results, Nov 2026 Watch for the guidance upgrade management flagged for Q2. |
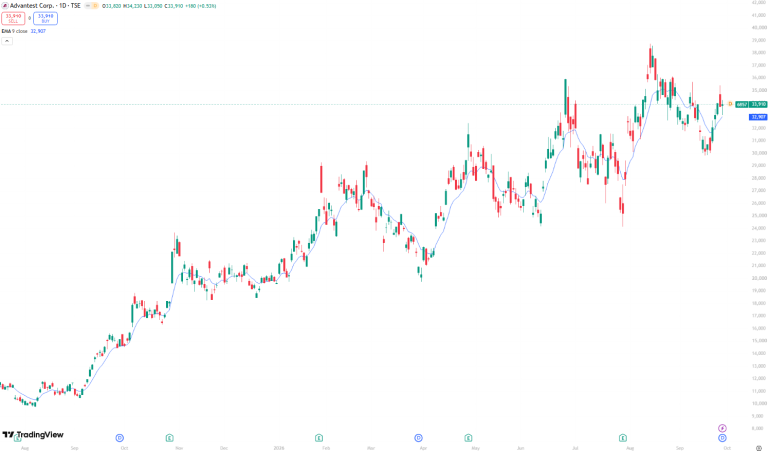
Advantest Corp (TSE: 6857)
WHY IT IS IN FOCUS
A semiconductor-testing company connected to advanced computing and AI infrastructure.
WHAT TO MONITOR
- Order intake and backlog mix — disclosed in the quarterly Q&A, not the release
- Customer concentration and the HBM/DRAM versus SoC tester split
- Gross margin and sales mix, the driver of the Q1 margin jump
- Capacity utilisation against the 10,000-systems-by-2028 plan
- CY2026 tester-market sizing and any guidance change on 28 Oct
BULL CONSIDERATIONS
- FY3/26 revenue ¥1,128.6bn (+44.7%); operating profit ¥499.1bn (+118.8%)
- Q1 FY26 net income ¥174.8bn, +93.8% YoY — record quarter
- FY2026 guidance raised to about ¥1,420bn revenue on AI tester demand
- Capacity expanding toward 10,000 systems a year by end-2028
BEAR CONSIDERATIONS
- ~40x earnings and ~17.7x sales leave no room for a demand pause
- Demand concentrated in a few AI/HBM customers (TSMC, Samsung, SK Hynix chains)
- 52-week price swing shows how violently the cycle re-rates
- Capacity build-out becomes fixed cost if AI capex slows
KEY DATA
SHARE PRICE / MARKET CAP ¥33,060 · ¥21.8trn Close 24 Sep 2026; larger market cap than Mitsubishi Corp. | FY3/26 ACTUAL ¥1,128.6bn, +44.7% Operating profit ¥499.1bn, +118.8%; net margin about 33%. | Q1 FY26 (APR-JUN) ¥367.5bn, +39.3% OP ¥190.0bn +53.3%; net income ¥174.8bn +93.8%. |
FY2026 GUIDANCE ~¥1,420bn revenue Raised at Q1 on AI inference, ASIC, CPU and DRAM test demand. | VALUATION ~40x PER · 17.7x P/S Consensus fair value clusters ¥32,700–34,000 — near the current price. | NEXT CATALYST H1 results, 28 Oct 2026 V93000 SoC tester share and CY2026 tester-market sizing. |
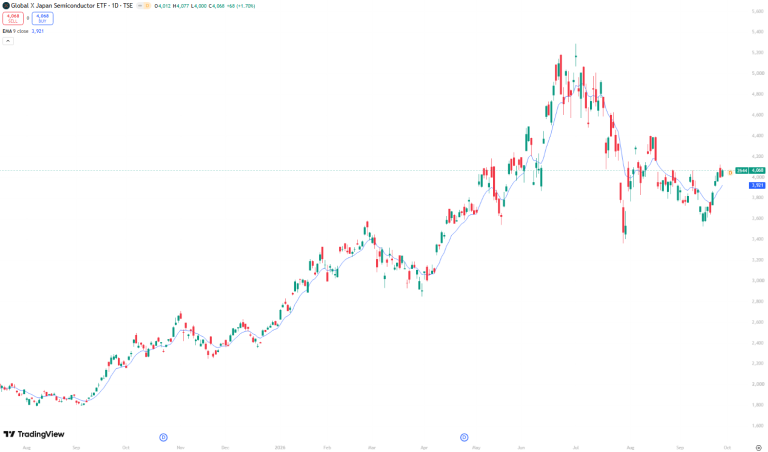
Global X Japan Semiconductor ETF (TSE: 2644)
WHY IT IS IN FOCUS
A diversified route to Japan’s semiconductor ecosystem.
WHAT TO MONITOR
- Monthly holdings file: Advantest’s weight and whether top-10 stays near 80%
- FactSet index rebalance dates and any methodology change
- Premium or discount to iNAV and daily volume before sizing an order
- AUM trend — inflows and outflows as a sentiment read
- Distribution at the 24 Oct record date
BULL CONSIDERATIONS
- 42 holdings across testing, equipment, materials, memory and analogue chips
- Total return +76.7% over one year; +27.5% a year since Sep 2021 inception
- ¥81bn AUM and ~694k shares daily volume — genuinely liquid
- Captures equipment names (Tokyo Electron, Disco, Lasertec) a single stock cannot
BEAR CONSIDERATIONS
- Top 10 are 80.1% of the fund — diversification is narrower than 42 names implies
- Advantest at 13.4% is the largest holding, doubling up on stock idea 2
- 52-week range ¥2,161–5,288; beta 1.19 — expect drawdowns of this size
- 29.3x earnings and 0.649% fee on a fully global-capex-dependent basket
KEY DATA
FUND SIZE / INCEPTION ¥81.1bn · 24 Sep 2021 Five-year track record; price ¥3,963 on 24 Sep 2026. | TOTAL EXPENSE RATIO 0.649% p.a. 0.59% before tax; semi-annual distributions, 24 Apr and 24 Oct. | HOLDINGS 42 names · top 10 ≈ 80% Advantest 13.4%, Lasertec 9.7%, Tokyo Electron 9.3%, Disco 9.3%. |
PERFORMANCE +76.7% over 1 year +54.1% YTD; +27.5% annualised since inception. | VALUATION / YIELD 29.3x PER · 0.56% Trailing distribution ¥22 per unit; payout ratio about 16%. | VOLATILITY CHECK ¥2,161 – ¥5,288 52-week range, beta 1.19 — position size for a cyclical basket. |
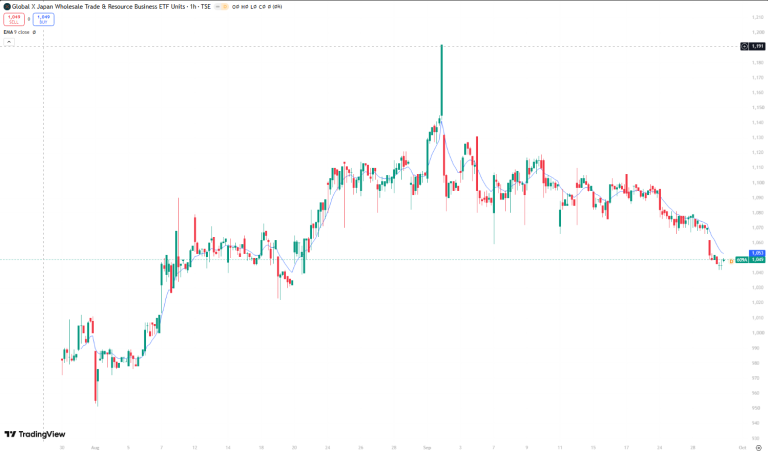
Global X Japan Wholesale Trade & Resource Business ETF (TSE: 609A)
WHY IT IS IN FOCUS
A diversified route to Japanese general trading companies and resource-related businesses.
WHAT TO MONITOR
- Full holdings file: how the 5–15% name and 60% category caps bind in practice
- AUM growth from the ¥0.71bn base — the viability and spread question
- Bid-ask spread and iNAV premium/discount; use limit orders
- Oil, copper and gold prices driving INPEX and Sumitomo Metal Mining
- First distribution at the 10 Jan 2027 record date
BULL CONSIDERATIONS
- Direct, single-trade access to all five major sogo shosha plus resource producers
- Index rose 114.2% over the year to 30 Apr 2026; NAV +9.1% since 28 Jul launch
- 5–15% per-name caps prevent any single trading house dominating
- Designed as an inflation-resilient diversifier away from typical Japan equity exposure
BEAR CONSIDERATIONS
- Only 12 holdings; top five are about 72% of the fund
- AUM of roughly ¥0.7bn is very small — wide spreads and liquidity risk
- Launched 28 Jul 2026: no meaningful live track record yet
- 0.649% fee and direct commodity-price sensitivity (INPEX, Sumitomo Metal Mining)
KEY DATA
FUND SIZE / LISTING ¥0.71bn · 28 Jul 2026 Newly listed on TSE; NAV ¥109,115 per 100 units (18 Sep). | TOTAL EXPENSE RATIO 0.649% p.a. 0.59% before tax; distributions each 10 Jan and 10 Jul. | HOLDINGS 12 names · top 5 ≈ 72% INPEX 15.2%, Sumitomo Metal Mining 14.7%, Itochu 14.2%, Mitsui 13.9%. |
MITSUBISHI CORP WEIGHT 13.6% Stock #1 is also the fund’s fifth-largest position — deliberate overlap. | SECTOR SPLIT 62% / 21% / 17% Industrials, basic materials, energy; 5–15% cap per name, 60% per category. | INDEX PERFORMANCE +114.2% over 1 year To 30 Apr 2026; +50.6% over six months — the theme has already run hard. |
What every investor should understand before going further
Continue exploring the themes shaping Japan’s markets with Japan in Focus, where you’ll find our latest bi-weekly breakdowns of two stocks and two ETFs, alongside past editions.
When you’re ready to put your research into action, explore Japanese stocks and ETFs on NOVA, with free market data and no platform fee.